What is the Direct Reduced Iron Market and why is it essential to the modern steel industry?
The Direct Reduced Iron (DRI) Market represents a critical segment of the global metallurgical sector. DRI, often referred to as sponge iron, is produced through the reduction of iron ore in the solid state by using reducing gases or coal. This high-purity metallic product serves as a vital high-quality feedstock for electric arc furnace (EAF) steelmaking, which is increasingly replacing traditional, more carbon-intensive blast furnace routes. By providing a clean, consistent scrap substitute, DRI enables steelmakers to produce specialized high-grade steel products, making this industry a cornerstone of the global shift toward decarbonized steel production and improved metallurgical efficiency.
What is the current Direct Reduced Iron Market market size and long-term forecast?
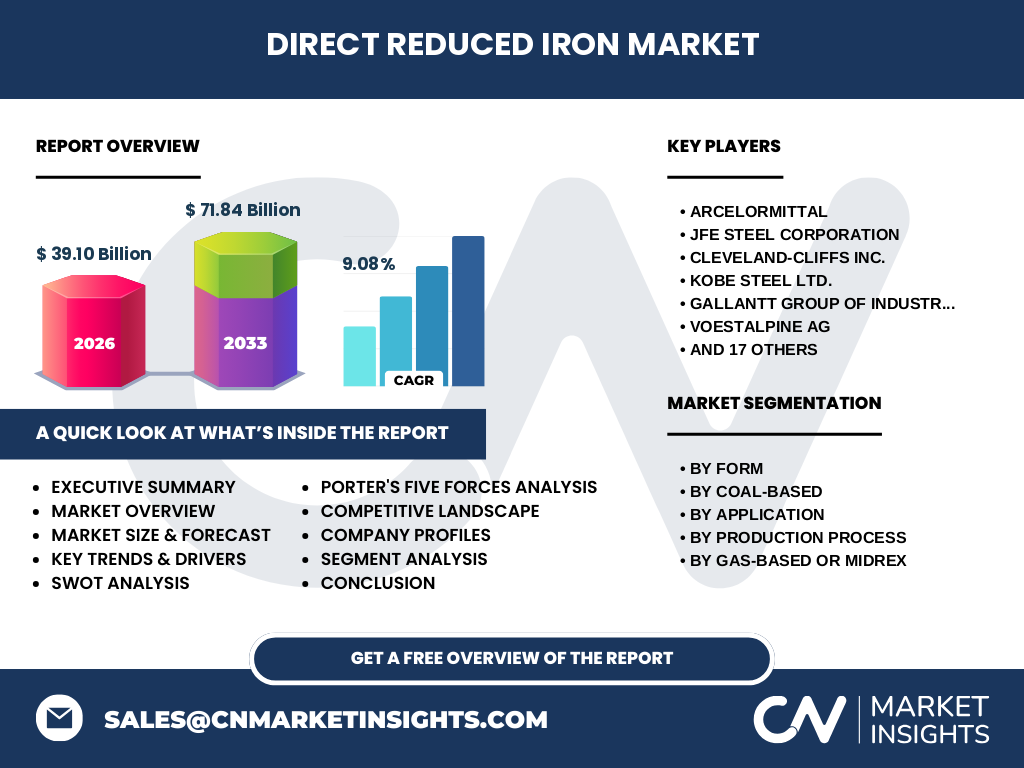
The Direct Reduced Iron Market is positioned for substantial expansion, reflecting the global transition toward cleaner steelmaking technologies. The market size is valued at 39.10 Billion in 2026. Looking ahead, our Direct Reduced Iron Market market forecast projects the sector to reach 71.84 Billion by 2033. This trajectory represents a robust CAGR of 9.08% over the 2027-2033 period, underscoring significant capital investment in capacity expansion and the widespread adoption of DRI-EAF integrated steel plants globally.
Which key factors are driving current Direct Reduced Iron Market trends?
Primary Direct Reduced Iron Market market trends are heavily influenced by the decarbonization mandate within the steel industry. Steelmakers are increasingly shifting toward EAF routes to reduce their carbon footprint, necessitating a steady supply of high-purity DRI. Technological advancements in gas-based production—such as the Midrex process—are improving energy efficiency and lowering operational costs. Furthermore, the rising demand for high-quality steel in automotive and infrastructure sectors requires premium raw materials that contain fewer contaminants than traditional recycled scrap, further accelerating the adoption of Direct Reduced Iron (DRI) From Coal and gas-based alternatives.
What are the primary challenges and commercial opportunities in the Direct Reduced Iron industry?
The Direct Reduced Iron (DRI) industry faces significant hurdles, primarily concerning the volatility of raw material prices and the high capital expenditure required for gas-based or Midrex infrastructure. Supply chain logistics for high-grade iron ore pellets also pose a constraint. However, these challenges create substantial opportunities in technological innovation focused on hydrogen-based reduction and optimized coal-gasification techniques. There is a burgeoning merchant trade market for Hot Briquetted Iron (HBI), which allows for safer transport of DRI, providing producers with a strategic path to supply global steel markets without the limitations of traditional iron sponge logistics.
How is the Direct Reduced Iron Market segmented for effective analysis?
Our Direct Reduced Iron Market analysis segments the industry into several critical categories. By form, the market is divided into Pellets and Lumps, each serving specific furnace charging requirements. The production process category distinguishes between Coal-Based and Gas-Based or Midrex technologies, which defines the sustainability and cost-profile of the product. Applications include Electric Arc Furnace (EAF) steelmaking, Basic Oxygen Furnace (BOF) or Blast Furnace (BF) charge enrichment, Hot Briquetted Iron (HBI) for merchant trade, and Foundry applications. Furthermore, our gas-based analysis specifically covers the Midrex process and HYL Process (HY-Lite), both of which are pivotal for modern, large-scale plant operations.
How do regional dynamics impact the global Direct Reduced Iron Market?
Geography is a definitive factor in the Direct Reduced Iron Market due to the proximity of iron ore reserves and the availability of affordable natural gas or coal. Regions with abundant natural gas resources, such as the Middle East, have become massive hubs for gas-based or Midrex production, while nations with significant coal reserves lean toward coal-based sponge iron production. Industrial infrastructure, government trade policies, and carbon tax regulations vary by region, creating a fragmented yet interconnected global market where companies like Mobarakeh Steel Company, Tosyali Algeria, and Jindal Shadeed Iron & Steel LLC utilize local resource advantages to secure competitive positioning.
What does the competitive landscape look like in the Direct Reduced Iron Market?
The competitive environment features a mix of global steel giants and specialized DRI producers. Key industry players include ArcelorMittal, JFE Steel Corporation, Cleveland-Cliffs Inc., Kobe Steel Ltd., Nucor Corporation, and Voestalpine AG, alongside specialized engineering firms like Midrex Technologies Inc. and Tenova SpA. Other notable participants include Gallantt Group of Industries, Ternium SA, Mobarakeh Steel Company, Hadeed Steel Industries, Jindal Steel and Power Ltd, Qatar Steel Company, Salzgitter AG, Jindal Shadeed Iron & Steel LLC, Tosyali Algeria, Tata Sponge, Tuwairqi Steel Mills Limited, JSW Ispat Special Products Limited, AM/NS India, Khouzestan Steel Company, and Essar Steel. Competitive advantage is driven by proprietary reduction technology, integration with iron ore assets, and the ability to scale production for the growing global EAF demand.
What specific intelligence is included in the full paid report for the Direct Reduced Iron Market?
The full report offers a comprehensive Direct Reduced Iron Market analysis, providing granular insights beyond the public overview. Readers gain access to detailed market forecasts through 2033, extensive segment-level analysis, and strategic competitive benchmarking of the listed industry leaders. The report details regional production capacity, cost-benefit analyses of different production processes, and identifies emerging technological risks and investment opportunities. It is an essential resource for stakeholders aiming to understand the specific dynamics of the Direct Reduced Iron Market, from raw material sourcing strategies to the future of HBI trade and the adoption of low-carbon steelmaking pathways.